This platform provides academic content only and does not constitute financial or investment
advice of any kind.
The scholars and practitioners who shaped this platform
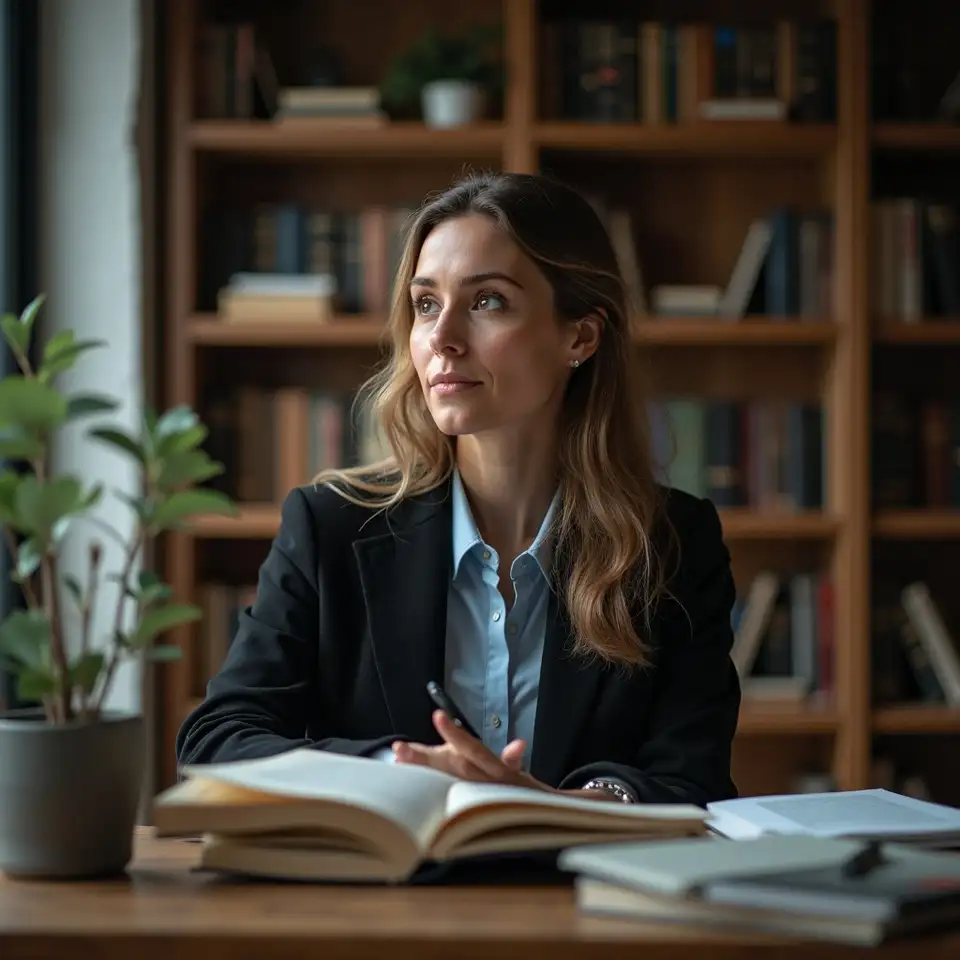
Dr. Marguerite Ellison, Founding Director of Research
Recursive utility theory and equilibrium asset pricing
Marguerite spent more than a decade working at the intersection of macroeconomics and asset pricing, with a particular focus on long-run risk models and their empirical implications. She founded this platform after observing that the most consequential theoretical advances were reaching almost no one outside specialist journals. Her approach insists on rigour without condescension.
Recognition and academic endorsements
Academic Outreach Commendation
2022Research Clarity Recognition
20232024
Excellence in Financial Theory Communication
Awarded by the Asia-Pacific Financial Education Council in recognition of the platform's commitment to making recursive utility and equilibrium asset pricing theory accessible to serious learners across the region, while maintaining the rigour of primary academic literature.
Theoretical Finance Contribution
2021Institutional Partnership Award
2025What this platform stands for
Five commitments that shape every explanation, every model, and every decision made here
Intellectual Depth
Recursive utility models are not simple, and this platform does not pretend otherwise. Every explanation is built to honour the actual complexity of the theory — separating risk aversion from intertemporal substitution, tracing the implications for stochastic discount factors, and following the logic wherever it leads. Depth is not a barrier here; it is the point. Learners who arrive with serious questions deserve serious answers, built from the ground up rather than assembled from convenient summaries.
Academic Integrity
Every claim made on this platform traces back to primary literature. The work of Epstein, Zin, Bansal, Yaron, and their contemporaries is treated with the care it deserves — cited accurately, explained faithfully, and never distorted for the sake of accessibility. When a model has limitations, those limitations are acknowledged. When empirical evidence is mixed, that complexity is preserved rather than smoothed over for a cleaner narrative.
Learner Respect
The audience for this material is not a general one. Practitioners, researchers, and
advanced students who engage with recursive preference models already understand a
great deal. This platform speaks to them as peers — not talking down, not
oversimplifying, and not padding explanations with material they have already
mastered. That respect for the learner's existing knowledge is a design
principle, not an afterthought.
Rigorous Clarity
Clarity and rigour are not opposites. The platform's central conviction is that the most demanding theoretical content can be explained with precision and without sacrificing the underlying mathematics. Building that kind of explanation takes longer and requires more care than summarising a paper in plain language. It also produces something more durable — an understanding that holds up when the learner encounters the primary source.
Open Inquiry
Asset pricing theory is not settled. Debates about the right way to model recursive preferences, the appropriate calibration of risk aversion parameters, and the empirical fit of long-run risk models are ongoing. This platform engages with that uncertainty honestly, presenting competing perspectives and unresolved questions rather than a single authoritative view. Genuine understanding requires knowing where the edges of knowledge are.
Start building your understanding of asset pricing
Recursive utility models reward careful study. Begin with the foundational
frameworks and follow the logic through to equilibrium prices and risk premiums, at
your own pace.
All platform content is freely
explorable — no commitment needed to begin.